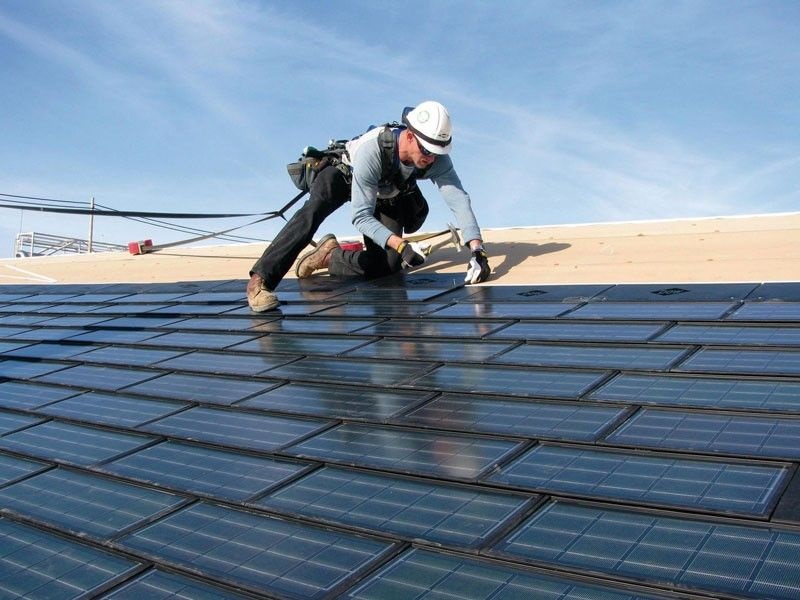

For a long time, a roof claim in Texas followed a simple pattern. A storm came through, an adjuster came out, a check arrived, and a new roof went on. That pattern has changed. Insurers now look closely at the roof itself, including its age, material, and condition, before they weigh what the storm did to it. Two houses on the same street, hit by the same hail, can end up with very different outcomes because one roof is eight years old and the other is eighteen.
The biggest change is in how deductibles work. Most Texas policies now use a wind and hail deductible based on a percentage of the home’s insured dwelling value, usually between 1 and 5 percent, and 2 percent has become the norm with many carriers. On a home insured for $400,000, that works out to $8,000 before the insurer pays anything. The figure has nothing to do with what the roof repair costs. As a result, many moderate storm repairs never reach the point where a claim makes financial sense, and the homeowner pays for them directly.
For homeowners in Montgomery, Conroe, Magnolia, and nearby communities who want a clear read on where their roof stands, Cedar Rock Roofing is a veteran-owned contractor based right in Montgomery. The company handles everything from patching leaks and damaged shingles to full replacements. After a storm, the crew inspects the roof, documents what they find, and walks owners through the insurance process. They are local, not a storm-chasing outfit, and estimates are free. Get the inspection on the calendar before the next front comes through, so you’re working from real information rather than guesswork.
The second change is in how older roofs get paid out. Many carriers now settle claims on roofs past a certain age at actual cash value instead of replacement cost. Fifteen years is a common cutoff for asphalt shingles. Actual cash value subtracts depreciation, so an aging roof may bring in a small fraction of what a new one costs. Some policies go a step further and use a roof payment schedule, which sets the payout from a fixed table based on age and material. Cosmetic damage exclusions are also more common. Hail dents in metal roofing or gutters that don’t cause leaks may not be covered at all.
Repair Work Carries More Weight Than It Used To
When small problems are likely to be paid out of pocket either way, it pays to catch them early. Southeast Texas is hard on roofs in ways that have nothing to do with hail. Constant humidity supports the algae that causes dark streaks on north-facing slopes. Heavy pine cover sheds needles that collect in valleys and hold moisture against the shingles. Long summers bake the underside of the roof deck, which wears out shingle adhesive and makes tabs easier to lift in the gusty winds that come with Gulf systems. Flashing around chimneys, skylights, and plumbing vents fails more often than the shingles themselves, and a small drip there can rot decking for months before a ceiling stain appears.
Records of maintenance are more useful than most owners expect. Dated photos, repair invoices, and inspection notes show that the roof was cared for. That can matter when an adjuster tries to decide whether damage came from the storm or from long-term wear. Keep in mind that a repair does not change the roof’s age on paper. A well-patched eighteen-year-old roof is still an eighteen-year-old roof to the underwriter. Repairs protect the house, but they don’t reset the calendar.
When Replacement Becomes the Better Spend
Once a roof nears the age where coverage shifts to depreciated value, replacing it becomes a question of the whole policy, not just the roof. A new roof restores replacement cost coverage on most policies. It can also keep a home insurable with carriers that are pulling back from older roofs.
Material choice matters more than it used to. Impact-resistant shingles rated Class 4 under the UL 2218 test standard can qualify for premium discounts with many Texas insurers. The Texas Department of Insurance keeps a list of qualifying products, and the credit usually requires paperwork showing what was installed. These shingles cost more upfront, but over the life of the roof the premium savings can cover a large share of the difference. The rest of the system counts too. Underlayment, attic ventilation, drip edge, and starter strips all affect how well a roof holds up to wind uplift, and a roof installed with poor ventilation tends to age early in this climate no matter which shingle is on top.
Matching is another reason full replacement sometimes wins out. Shingle lines get discontinued, and colors weather differently over time, so a patched section on a ten-year-old roof may never blend in. Whether a policy pays to make a repair match depends on the policy’s wording, so it’s worth asking your agent before any work starts.
What a Useful Storm Inspection Includes
A good post-storm inspection is methodical. On the roof, inspectors often mark test squares on each slope and count the hail hits inside them, since carriers look for a consistent pattern rather than scattered marks. Soft metals like vent caps, gutters, downspouts, and air conditioner fins show hail size and direction well, and they help separate a true storm event from normal aging. Inside, the attic can show daylight coming through, wet insulation, or water trails along the rafters that can’t be seen from the ground.
Timing matters. Many Texas policies set a window for reporting weather damage, often one year from the date of loss. Waiting until the next storm makes it hard to show which event caused what. Photograph everything with dates visible and keep copies of every estimate.
Texas law also bars contractors from waiving, rebating, or covering a homeowner’s insurance deductible. An offer to “take care of the deductible” is a warning sign, not a perk, and it’s more common from out-of-town crews that follow storms from city to city.
Before the next storm season, the most useful thing any homeowner can do is simple. Read the declarations page, find the wind and hail deductible and the roof settlement terms, and confirm the year the roof was installed. Those three facts will shape what happens after the next storm far more than the storm itself.